# ESG
Perma-Pipe’s board appointments: evaluating expertise and oversight
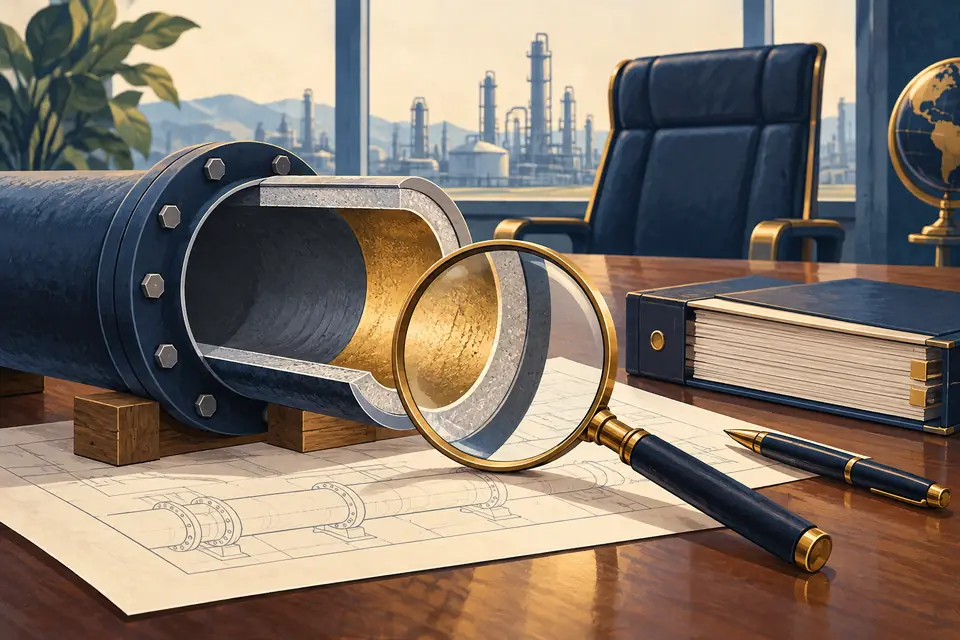
The April 2026 appointments raise practical questions about committee responsibilities, project risk, and capital allocation.
Reuters reported on May 25, 2026, that shares rose while oil and the dollar weakened as investors responded to prospects for an agreement to end the Iran war. The report also identified uncertainty over reopening the Strait of Hormuz. On May 26, Reuters described higher oil prices and mixed stocks after renewed U.S. strikes tempered that optimism. [1][2]
Markets do not wait for every outcome to become certain. A perceived increase in the likelihood of restored shipping can reduce the premium buyers pay for possible supply disruption. That can support businesses whose costs are sensitive to energy prices.
The reverse can occur when new information undermines negotiations. A rally therefore does not confirm that an agreement exists, that it will last, or that transport conditions have normalized.
Oil reflects supply, demand, inventories, and transport risk. Equities also reflect expected company earnings and discount rates. Currency moves can reflect interest-rate expectations and demand for liquid assets. Describing all of them as a single vote of confidence conceals those differences.
Implementation matters: access to shipping routes, insurance availability, security guarantees, and actual export volumes. For companies, a headline agreement does not instantly remove higher freight bills or replenish inventories. These two trading sessions illustrate the sensitivity of market prices to diplomatic news, rather than proving that the underlying conflict or its economic effects had ended.
Sources support the dates and events discussed. This post is not a live update. Financial examples and analysis are for general information. Article images are AI-generated editorial illustrations, not photographs of the events or people discussed.
For factual corrections, see our corrections policy.
The April 2026 appointments raise practical questions about committee responsibilities, project risk, and capital allocation.
A coalition of states and local governments challenged the repeal of the endangerment finding and vehicle standards.